
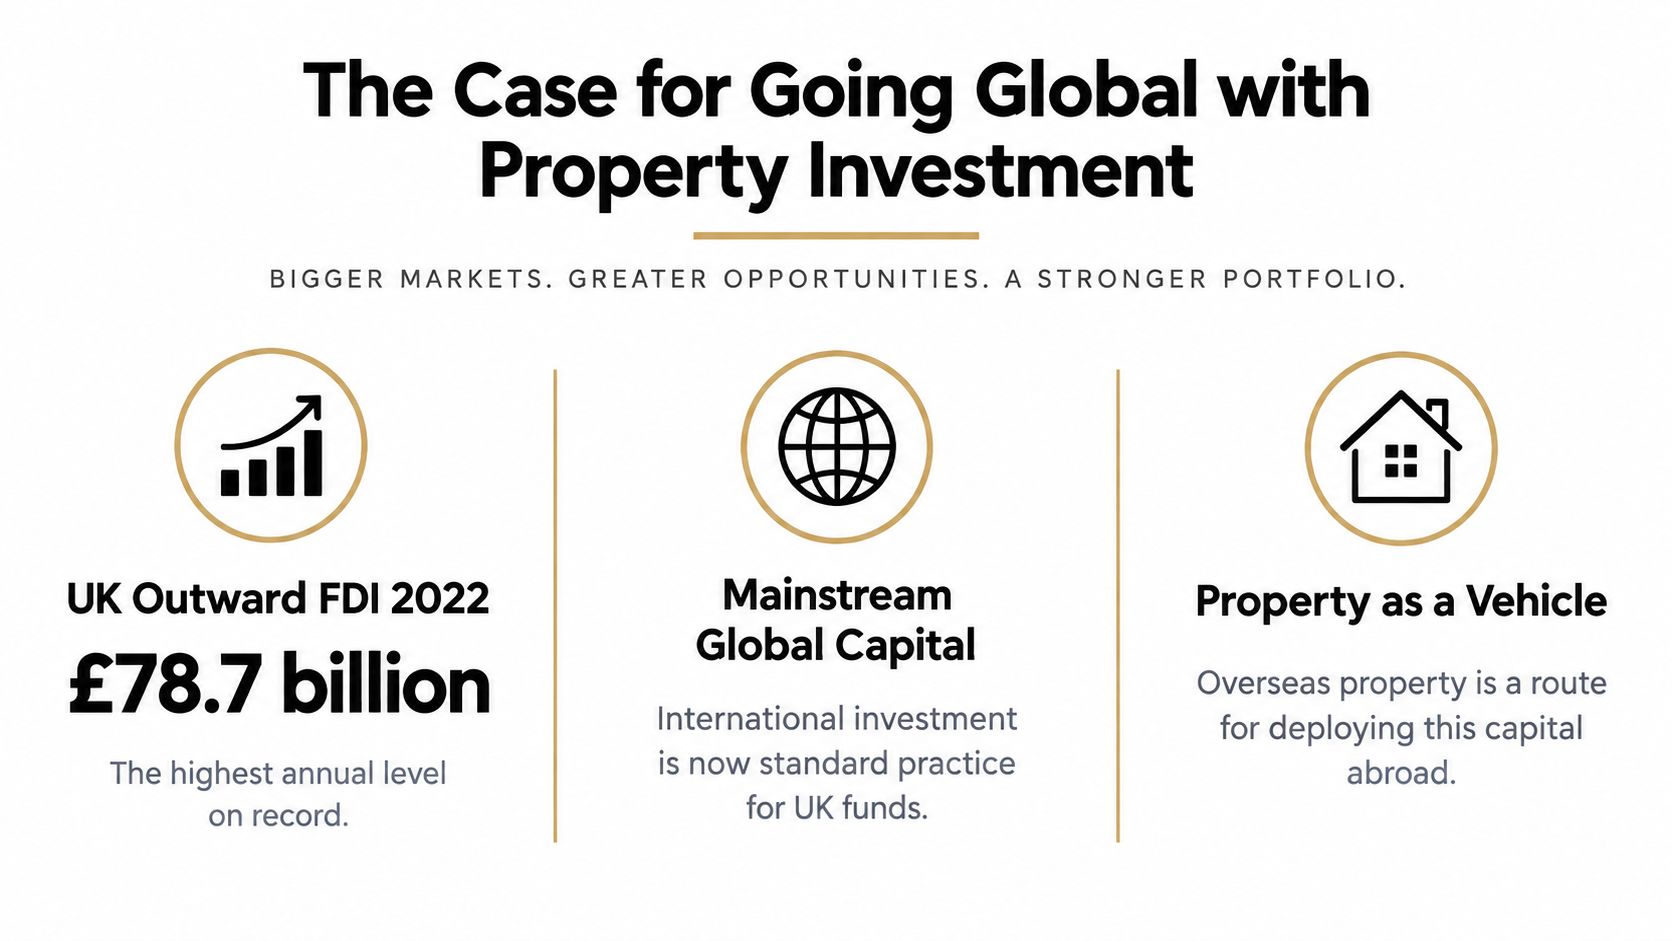
In 2022, UK outward foreign direct investment reached £78.7 billion, the highest annual level since 2017. That figure shows why investing abroad is a mainstream capital strategy, not just a speculative move for adventurous property buyers.
The more useful question isn't whether overseas property can produce an attractive rent. It's which risk you want to reduce, which objective you want to achieve, and whether direct property is the right vehicle for it. A foreign villa may diversify your exposure to UK house prices, but it can also deepen your exposure to illiquid real estate, landlord obligations and currency movements.
UK investors therefore need a broader framework. Income, resilience, capital preservation and mobility can all justify an international allocation, but they require different markets and different due diligence.
Table of Contents
- The Case for Going Global with Property Investment
- Does Overseas Property Really Diversify Your Portfolio
- Investing Abroad for Income, Resilience, and Mobility
- Comparing Established and Emerging Property Markets
- Evaluating Legal Systems, Ownership Rules, and Currency Risks
- Building a Balanced International Property Portfolio
- Starting Your First Overseas Property Investment
The Case for Going Global with Property Investment
The £78.7 billion figure comes from Office for National Statistics data on UK outward foreign direct investment. UK outward FDI rose from £61.4 billion in 2021 and reached its highest annual level since 2017, according to the ONS methodology for foreign direct investment. The United States received £30.9 billion, while the Netherlands received £12.9 billion.
Outward FDI measures investment by UK-resident companies in overseas businesses where the investor intends to maintain a lasting interest. It doesn't describe individual buyers purchasing a flat in Spain or a holiday home in Florida, but it establishes an important precedent. UK capital has long moved across borders to reach different economies, industries, companies and income sources.
The scale continued into the following years. At the end of 2024, UK-resident companies held £1,856.1 billion in outward FDI stock, up from £1,839.0 billion in 2023, as reported in the ONS foreign direct investment statistics for 2024. That is more than £1.8 trillion invested in overseas companies and productive assets.
Why the precedent matters to property buyers
A private investor doesn't have the balance sheet of a multinational, but the underlying logic is similar. International allocation can provide access to:
- Different economic cycles: A local property market may respond to employment, tourism, demographics and interest rates that don't move in step with Britain.
- Broader income sources: Rent or business income from another country isn't tied entirely to UK wages, tenants or domestic demand.
- New opportunities: Larger economies and growing cities may offer property types that are scarce or expensive in the UK.
- Currency exposure: Foreign assets can introduce another currency, which creates risk but may also reduce dependence on sterling.
That doesn't make every overseas purchase sensible. A poorly managed apartment in a restricted market remains a poor investment, wherever it's located. It does mean overseas property belongs within a long-established international investment tradition rather than being treated automatically as an exotic gamble.
For readers comparing domestic options before allocating capital abroad, a discreet home search in London can provide useful context on how much exposure a UK residential purchase would add. Investors can also review a practical guide to overseas property investment before comparing individual markets.
Does Overseas Property Really Diversify Your Portfolio
International property changes location, but location alone does not create a diversified portfolio. A second building abroad can leave an investor exposed to the same asset class, financing pressures, maintenance demands and illiquidity as a domestic purchase.
The starting point matters. J.P. Morgan Asset Management places UK household assets held in property at about 50%, compared with 33% in the US. McKinsey estimates the UK figure at approximately 60%, against roughly 50% globally, as discussed in its analysis of the UK savings opportunity. Estimates vary by methodology, but the message is consistent: many UK investors already hold substantial property exposure.
A property in Portugal may reduce reliance on UK house prices while increasing exposure to Portuguese regulation, local mortgages, maintenance contractors and tenant demand. A holiday villa adds seasonal occupancy risk. It may also take months to sell, unlike a listed fund that can generally be traded during market hours.
The useful question is not just, “Which country should I buy in?” Ask which concentration the purchase is meant to reduce.
- UK housing risk: A foreign property can help when its employment, tourism, demographic and interest-rate drivers differ meaningfully from Britain's.
- Sterling risk: Foreign income and capital values move with exchange rates, creating both a potential buffer and a source of loss when measured in pounds.
- Employment risk: Rental income adds another cash-flow source, but it may weaken during the same downturn that affects the investor's job or business.
- Asset-class risk: Global equities, bonds, infrastructure and cash may diversify property exposure more directly than another building.
The opportunity cost deserves equal attention. J.P. Morgan estimates that UK savings invested in a global stock portfolio could have generated a 93% real return over the referenced period. That figure is not a forecast or a guarantee, and equities carry their own risks. It does show why an overseas purchase should be compared with liquid global investments, not only with other properties.
A practical test is simple: if wealth is already tied to UK property, decide whether a foreign building solves that concentration or transfers it into a different legal and operating system. Use real-estate investment guides to frame the comparison, then allow for tax, fees, financing, management costs and illiquidity before committing capital.
Investing Abroad for Income, Resilience, and Mobility
Rental income is one objective, not the whole investment case. A property abroad can serve three distinct purposes, and each requires a different test.
For income generation, calculate net cash flow rather than relying on the advertised gross yield. Management, insurance, repairs, local taxes, financing, vacancy and currency conversion can materially reduce the amount received. A property with steady occupancy and moderate rent may produce more dependable income than a high-yield listing built around optimistic holiday-let assumptions.
Wealth preservation changes the priorities. Title security, construction quality, political stability, market depth and a credible resale route matter more than a low purchase price. A prime location with resilient local demand may preserve capital better than a cheaper emerging district whose resale depends on a narrow pool of overseas buyers.
Mobility introduces a personal and strategic dimension. A home near family, a business centre or a possible future base may justify ownership even when its financial return is not the highest available. Ownership does not automatically grant residency, work rights or tax residence. Confirm those issues separately with qualified legal and tax advisers.
The objective may also shift over time. Income can matter during the holding period, resilience can matter during a political or economic shock, and mobility can matter when family or business circumstances change. A property should therefore be judged by the role it is expected to play, not by yield alone.
HSBC's 2025 Global Wealth Hubs research found that 17% of UK entrepreneurs surveyed were considering moving some or all of their wealth to the United States within the next 12 months. The same study reported that 69% of entrepreneurs globally were considering moving wealth to a new location, as set out in the HSBC Global Wealth Hubs report. Its affluent, quota-based sample should not be treated as representative of all UK investors.
Score the property against its real purpose
Assess the opportunity across four tests:
- Cash flow: Can it attract tenants beyond peak periods, and what remains after operating costs?
- Resilience: Does demand come from several tenant groups or one vulnerable tourism segment?
- Mobility: Does the location support family, business or lifestyle plans, separate from any immigration benefit?
- Exit: Who might buy it later, and how easily can proceeds be converted and transferred?
Research for a specialist market can include REISR's investor guide to Israel alongside local legal and tax advice. The decision is whether the property earns its place through income, resilience, mobility, or a credible combination of them.
Comparing Established and Emerging Property Markets
Market maturity affects more than price. It influences the quality of legal records, mortgage availability, buyer depth, management standards and the ease of selling when circumstances change.
Mature European destinations such as Spain and Portugal often offer established professional services, familiar transaction processes and deeper resale markets. Their trade-off can be higher entry costs, stronger competition and less room for a headline yield to compensate for mistakes. Anglo-Saxon markets, including the UK and United States, may offer clearer documentation and broad financing ecosystems, though local tax and landlord rules still vary considerably.
Emerging European markets, including Greece and Turkey, can provide different growth stories and potentially stronger gross income opportunities. They may also expose buyers to changing regulations, more complex title checks, currency movements and uneven investor protections. Growing Asian cities can offer expanding employment and rental demand, but the foreign buyer must examine ownership structures and local enforcement rather than relying on a broker's sales narrative.
| Market Tier | Typical Gross Yield | Growth Driver | Tax Complexity | Liquidity |
|---|---|---|---|---|
| Mature European markets | Varies by city and property type | Established tourism, employment and international demand | Moderate to high, depending on ownership and letting model | Generally stronger in established centres |
| Anglo-Saxon destinations | Varies by city and neighbourhood | Employment growth, migration and deep capital markets | Moderate, with local and national rules to review | Often supported by broader buyer pools |
| Emerging European locations | Varies widely by asset and district | Tourism, infrastructure and urban regeneration | Can be higher because rules and reporting differ | Uneven, particularly outside major centres |
| Growing Asian cities | Varies significantly by market | Urbanisation, business activity and rising local demand | Often complex for foreign owners | Dependent on ownership rules and local financing |
The table deliberately avoids invented yield ranges. A reliable figure depends on the exact city, property, tenure, letting strategy and calculation method. Gross yield alone ignores the costs that determine whether an investment works.
Match market structure to the objective
For dependable income, look for diversified tenant demand, transparent operating costs and professional management. For capital appreciation, examine employment, infrastructure, planning and supply rather than relying on a recent price increase. For lifestyle utility, assess access, healthcare, transport and personal use restrictions before treating rental income as the main justification.
A market comparison is more useful when it records the downside as carefully as the upside. The emerging property markets guide can support initial research, but it can't replace a local inspection, independent valuation or jurisdiction-specific advice.
Evaluating Legal Systems, Ownership Rules, and Currency Risks
A foreign property purchase can fail before the first tenant arrives. The title may be incomplete, the intended use may be restricted, or the buyer may misunderstand what ownership permits.
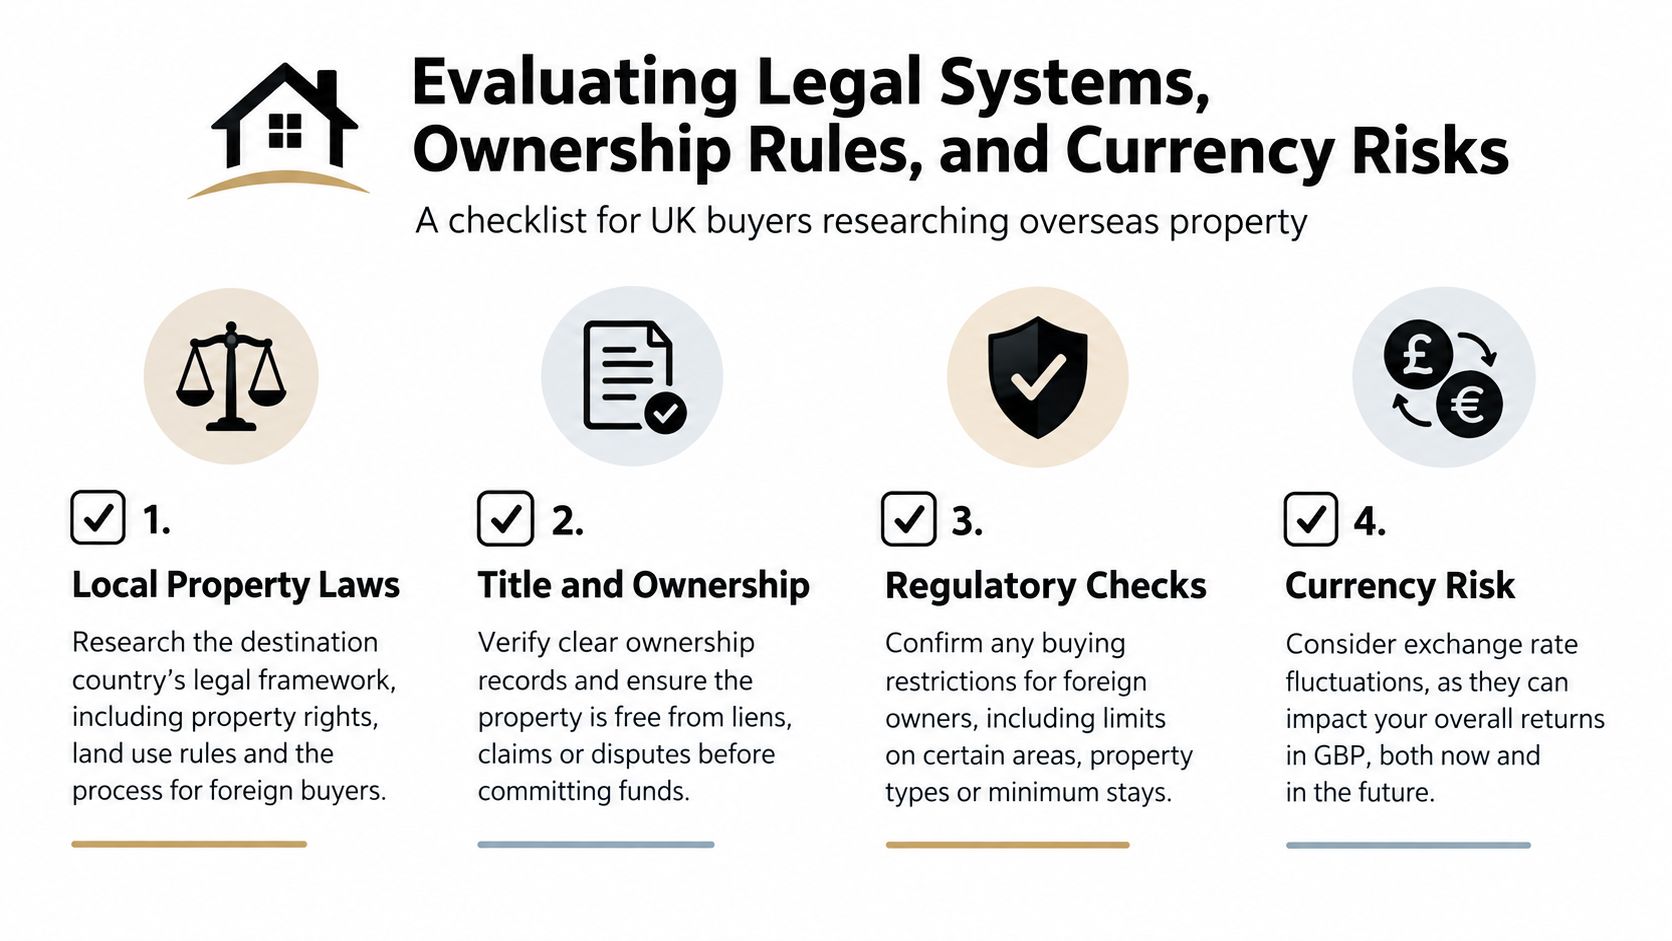
GOV.UK advises buyers to research local laws, confirm that the seller or developer owns the title deeds and can transfer them, and appoint an independent English-speaking lawyer who is licensed and experienced in the destination country. It also warns that some countries restrict foreign nationals from buying or renting property, as explained in the GOV.UK guidance for buying property abroad.
Complete the checks before paying a deposit
- Confirm local property law: Establish whether foreign buyers can own the land, the building, or only a leasehold interest.
- Verify title and seller authority: Ask an independent lawyer to check ownership records, liens, planning status and the seller's power to transfer the property.
- Test the permitted use: Confirm whether short-term letting, renovation, commercial operation or personal occupation requires additional approval.
- Model the currency: Calculate the purchase, mortgage, rent and eventual sale in pounds as well as the local currency.
Currency risk deserves a place in the initial investment model, not a footnote at completion. Sterling appreciation can reduce the pound value of foreign rent and sale proceeds. Sterling weakness can increase that value, but it can also raise the cost of local expenses, mortgage payments and future maintenance when those costs are funded from UK income.
Tax requires the same discipline. HM Revenue & Customs states that UK residents generally pay UK tax on foreign income, including overseas-property rent, and usually report it through Self Assessment, according to its guidance on foreign income. Foreign tax may be creditable, but relief isn't automatic or unlimited. HMRC's rules generally limit foreign tax credit relief to the lower of the foreign tax paid and the UK tax due on the relevant income or gain.
Before exchange: Get the purchase price, recurring costs, expected rent and exit proceeds translated into sterling under more than one plausible exchange-rate scenario.
Overseas property losses don't automatically offset UK property profits. HMRC's property-income manual on overseas property businesses states that profits and losses from overseas and UK property businesses aren't combined in that way. That can make a seasonal or heavily financed property less forgiving than the original sales brochure suggests.
Investors considering specialised incentives should also investigate the details with local counsel. For example, Act60 real estate guidance may help frame questions about Puerto Rico, but it isn't a substitute for advice on eligibility, tax residence or ownership structure. A wider review of foreign ownership restrictions by country should happen before negotiations become irreversible.
Building a Balanced International Property Portfolio
Direct overseas property can strengthen a portfolio, but it should rarely become its entire international allocation. A building takes longer to sell than a listed security, can be difficult to value in a quiet market, and relies on local agents, contractors, tenants, and regulators. Several properties in different countries may still share the same exposure to illiquidity, operating problems, and property-market cycles.
The ONS reported £85.7 billion of UK residents' portfolio investment abroad in 2024, while UK assets held overseas increased overall during the year. The largest movement was a £292.2 billion outflow in other investment abroad, according to the ONS Pink Book balance of payments data. These figures do not set an allocation for an individual investor. They do show why liquid international assets can complement direct property.
A practical structure might pair one carefully selected overseas property with global equities, bonds, funds, or cash reserves. The appropriate balance depends on objectives, borrowing, liquidity needs, and risk tolerance. Global equities can spread exposure across companies and economies, while property adds direct control and potential rental income, but also creates operational responsibility. The aim is diversification across countries and asset classes, not a collection of addresses that all depend on similar risks.
Test the return you can keep
Begin with gross rent, then deduct property management, insurance, maintenance, vacancy, furnishing, local and UK taxation, financing, utilities, service charges, currency conversion, and repatriation costs. A high advertised yield can look very different after these items.
Stress-test the result by reducing occupancy, increasing repair costs, varying the exchange rate, and allowing for a period without rent. If the investment works only under favourable assumptions, it is not resilient enough.
Tax treatment adds another reason to avoid excessive concentration. An overseas property loss generally cannot be set against UK property profits, so a weak foreign asset may remain a standalone drag on cash flow. Liquid holdings still carry market risk, but they can provide flexibility when a direct property cannot be sold quickly.
Personal concentration matters too. A UK home, UK buy-to-let, UK employment income, and a foreign holiday rental may react differently to household finances, yet they still leave the investor heavily exposed to property and operational demands.
The useful question is not how many countries you own. It is how many independent sources of risk and return your portfolio contains.
Starting Your First Overseas Property Investment
Begin with an objective, not a country. Decide whether the priority is rental income, capital growth, personal use, future relocation or a combination. A destination that suits a holiday home may be unsuitable for a hands-off rental investment, while a strong rental market may offer little personal value.
A first-time investor is usually better served by understanding one market properly than by spreading research across several countries. Select a city, identify the tenant or guest profile, inspect comparable properties and build a complete cost model before making an offer.
A practical first-purchase sequence
- Define the use case: Write down the target income, personal-use requirements, liquidity needs and intended holding period.
- Research the city: Review employment, tourism, transport, supply, planning and local letting rules.
- Build two return models: Separate gross yield from net yield, then test occupancy, costs, taxation and currency movements.
- Appoint independent advisers: Use a local lawyer and tax adviser who understand the host country and the UK reporting position.
- Inspect the asset: Verify construction, title, permitted use, service charges, access and likely maintenance before committing funds.
A buyer researching a coastal apartment might initially favour a high advertised yield. After checking seasonal demand, management charges and sterling conversion, a smaller property near year-round employment could prove more suitable. The decision isn't about finding the most exciting listing. It's about finding an asset whose income, legal position and personal purpose remain credible under less favourable conditions.
Use a detailed guide to buying overseas property to organise the early research, then obtain professional advice before signing contracts or transferring funds. Overseas property can add valuable international exposure, but it works best as one part of a broader plan rather than a substitute for global diversification.
World Property Investor provides country and city guides, market analysis, rental-yield breakdowns and practical buying guidance for comparing international property opportunities. Visit World Property Investor to research destinations, test investment assumptions and build a more informed overseas property strategy.